
How to Value a Medical Practice: The Essential Guide to Calculating True Profitability
Knowing how to value a medical practice can mean the difference between accepting 0.5x or 2.5x your annual revenue. More, practices with strong financials command EBITDA multiples ranging from 6x to 11x, while healthy profit margins fall between 20% and 30%. Accurate medical practice valuation requires more than a simple medical practice valuation calculator, whether you’re preparing for retirement or learning strategic growth options.
We’ve created this complete guide to walk you through valuation methods and critical profitability metrics for medical practice appraisals. You’ll learn how to calculate the value of a medical practice using multiple approaches and avoid mistakes that can get pricey when selling your medical practice.
Medical Practice Valuation Methods Explained
“The value of your practice isn’t determined by what you think it’s worth, or even what a formula suggests. It’s determined by what a qualified buyer is willing to pay.” — SovDoc, Healthcare valuation experts
Professional valuators rely on three main methodologies to determine medical practice worth. Each approach gets into different aspects of your business, and most appraisals combine multiple methods to arrive at a defensible final number.
Income approach and EBITDA calculations
The income approach focuses on your practice’s capacity to generate future economic returns. This methodology analyzes historical financial performance and projects future cash flows based on patient demographics, physician productivity and healthcare policies. Two techniques fall under this framework: capitalization of earnings and discounted cash flow (DCF).
Capitalization of earnings takes your normalized historical earnings and applies a capitalization rate that reflects the risk associated with receiving those future earnings. A lower risk profile means a lower capitalization rate and higher valuation. The DCF method projects future cash flows over several years and discounts them back to present value.
EBITDA multiples have become the dominant methodology because they show actual earning capacity after operational expenses. Medical practices trade at 6x to 12x adjusted EBITDA depending on practice size. Practices generating over $5M in EBITDA command 10x to 12x multiples, while smaller practices with $500K to $1M EBITDA see 6x to 8x multiples. Income-based valuation yields higher valuations than asset approaches for profitable practices that are managed well.
Asset-based valuation approach
This approach calculates value by adding all assets and subtracting liabilities. Tangible assets include medical equipment, office furniture, computers and real estate at fair market value. Medical equipment often represents 20% to 40% of total practice assets.
Intangible assets include your patient base, brand name and goodwill. Patient relationships and medical records generate recurring revenue streams but face restrictions on transferability due to healthcare privacy regulations. Asset-based valuation provides a practical value floor but undervalues operational practices with strong patient relationships. The approach is straightforward though.
Market comparison approach
The market approach compares your practice to similar practices sold recently. Valuators analyze transaction multiples, price-to-revenue ratios and other comparative metrics from comparable sales. Finding sufficient comparable data presents challenges because private practice sales often involve confidential terms.
Rule of thumb multiples
Rules of thumb offer quick directional estimates. Medical practices often sell for 0.5x to 0.9x gross annual revenue for general practitioners. EBITDA multiples provide a profitability-focused alternative, with practices trading at 4x to 7x adjusted EBITDA. Seller’s discretionary earnings multiples range from 2.5x to 3.5x SDE. Some buyers use per-physician metrics ranging from $200,000 to $500,000 per full-time equivalent physician.
Key Factors That Drive Your Practice Value
Buyers assess practices through a practical lens: which earnings will survive after ownership changes. Two practices generating similar revenue can receive valuations differing by $2 million based on risk factors.
Revenue quality and payer mix
Payer composition determines both profitability and risk exposure. Practices with over 60% commercial insurance achieve 7x to 9x EBITDA multiples. Those with majority Medicare exposure receive 5x to 6x multiples. Commercial insurance reimburses 89% higher than Medicare rates. A balanced mix signals stability, whereas heavy reliance on a single payer introduces vulnerability to reimbursement changes.
Concentration risk matters. Buyers view this as a major liability if one insurance contract represents 40% of total income. Medicaid-heavy practices face the steepest discounts due to lowest reimbursement rates and administrative complexity.
Provider dependency and transition risk
Buyers reduce offers when more than 60% of revenue runs through a single provider. Practices with stable production across multiple clinicians prove easier to value than those where the revenue engine concentrates in one person. Associate-driven models receive 1 to 2 additional multiple turns because they show sustainability beyond current ownership.
Operational efficiency metrics
Overhead ratios vary by specialty: 50% to 60% for primary care and 40% to 50% for specialty practices. Collection rates should exceed 95%. Rates below 90% show significant billing problems. Days in accounts receivable under 40 days signals operational maturity.
Specialty and service line considerations
Surgical specialties sell for 26% premiums compared to primary care practices. Dermatology and ophthalmology command premium multiples due to favorable reimbursement models. Ancillary services like ASCs, imaging, or labs add 1 to 3 multiple turns.
Geographic location and market demand
Urban practices in high-demand areas receive higher valuations than rural locations. Markets with limited competition and strong household income attract more buyers.
How to Calculate Your Practice’s True Profitability
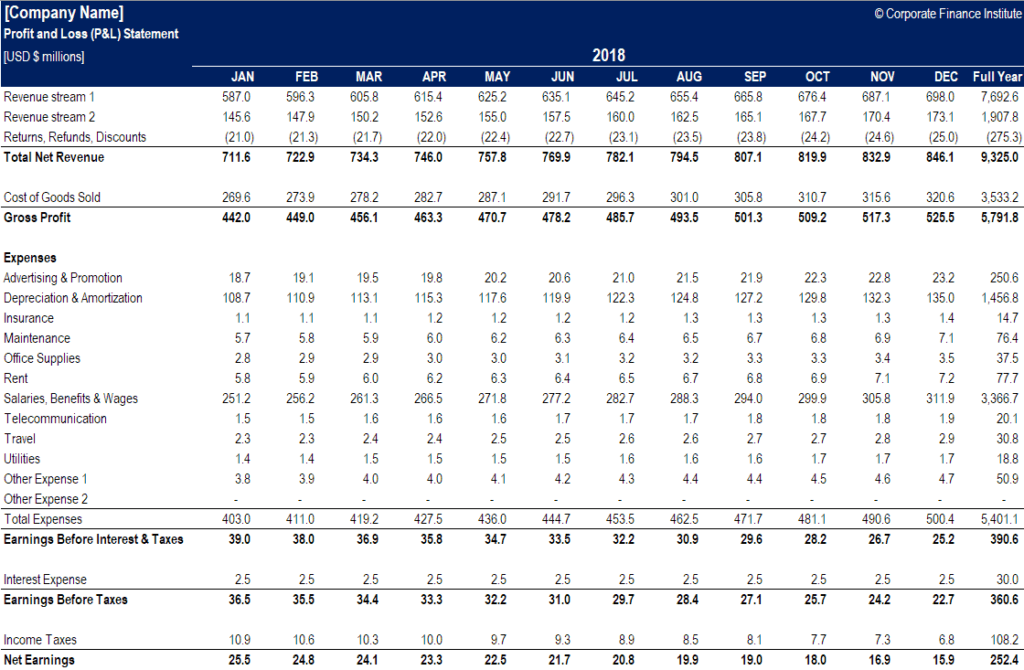
Accurate medical practice valuation starts with measuring what you earn. Financial experts break practice profitability into four distinct levels that reveal where money enters and exits your operation.
Understanding the 4 levels of practice profitability
Gross revenue represents total billed amounts before any deductions. Net revenue shows cash collected after contractual write-offs and bad debt. Operating profit (EBITDA) strips out expenses outside your direct control and reflects core operational profitability. Buyers use this metric to determine market value. Net profit is your final bottom line after all expenses, taxes and depreciation. Practices that run smoothly maintain EBITDA margins between 20% and 35%. Primary care averages 15% net margin, and specialty clinics achieve 25% to 40%.
Critical financial KPIs to track
Revenue per provider measures individual clinician contribution. Patient lifetime value (LTV) guides marketing investment decisions. Payer mix analysis shows revenue percentage from each source. Net collection rate should exceed 95%. Overhead ratio runs 60% to 70% of revenue depending on specialty.
Calculating gross and net profit margins
Gross profit margin equals total revenue minus cost of care, divided by total revenue, multiplied by 100. Net profit margin uses total revenue minus all expenses, divided by total revenue, multiplied by 100. Operating margin before owner compensation provides the most useful comparison metric.
Revenue cycle management metrics
Days in accounts receivable should stay between 30 and 40[151]. Claims denial rates under 5% signal clean operations[151]. Track A/R over 120 days and keep it below 12%.
Steps to Prepare for a Medical Practice Appraisal
Preparation typically begins several years before a transaction. Starting early gives you time to address fixable operational issues and maximize your outcome.
Organizing financial documentation
You’ll need to gather three to five years of financial statements, tax returns, and detailed profit and loss reports. The valuation process takes four to eight weeks depending on documentation quality. Provider compensation details, payer contracts with fee schedules, patient demographic and volume data, and accounts receivable aging reports are essential. Revenue cycle analysis that shows payer mix, collection rates, and operational cost breakdowns supports accurate value conclusions. Practices that close books monthly and produce financials within two weeks signal operational maturity to buyers.
Normalizing earnings and expenses
Your existing compensation structure should be replaced with market-based salary standards from MGMA or SullivanCotter. Personal expenses like travel, vehicles, and family member salaries that run through the business need removal. One-time costs including legal fees, office relocations, or unexpected repairs should be eliminated. Every adjustment requires documentation with invoices, market data, and lease agreements. Aggressive or questionable adjustments erode trust during due diligence.
Working with valuation professionals
You should involve a CPA with healthcare experience or dedicated valuation firm. Professional valuators provide unbiased assessments, understand industry regulations, and produce defensible reports that withstand buyer scrutiny. They access comparable transaction databases unavailable publicly.
Common mistakes to avoid
Inadequate EBITDA normalization and poor financial documentation raise buyer concerns. Unrealistic multiple expectations using outdated standards, inadequate preparation time, and failing to demonstrate sustainability beyond current ownership derail transactions.
Timing your valuation strategically
Pre-sale planning should begin two to three years before your intended transaction. Valuations need annual updates and whenever most important operational changes occur.
Conclusion
Valuing a medical practice requires nowhere near just plugging numbers into a formula. Your practice value depends on normalized EBITDA, payer mix quality and operational efficiency. Start your valuation process at least two years before any planned transition. This timeline gives you room to address operational weaknesses and boost your final outcome. Professional guidance combined with clean financials will help you capture the worth of what you’ve built.
Key Takeaways
Understanding your medical practice’s true value is critical whether you’re planning retirement, seeking growth, or exploring sale options. Here’s what every practice owner needs to know:
• Valuation varies dramatically: Medical practices sell for 0.5x to 2.5x annual revenue, with strong practices commanding 6x to 11x EBITDA multiples—proper preparation makes the difference.
• Multiple methods reveal true worth: Professional valuations combine income approach (EBITDA multiples), asset-based calculations, and market comparisons rather than relying on single formulas.
• Revenue quality trumps quantity: Practices with 60%+ commercial insurance achieve 7x-9x EBITDA multiples versus 5x-6x for Medicare-heavy practices due to reimbursement differences.
• Provider dependency kills value: When one provider generates over 60% of revenue, buyers significantly reduce offers; multi-provider models command 1-2 additional multiple turns.
• Start preparation 2-3 years early: Organize 3-5 years of financials, normalize earnings by removing personal expenses, and address operational weaknesses to maximize your final outcome.
• Track critical profitability metrics: Maintain EBITDA margins of 20-35%, collection rates above 95%, and days in A/R under 40 to demonstrate operational excellence to buyers.
The difference between accepting a mediocre offer and capturing your practice’s full value lies in understanding these fundamentals and working with experienced valuation professionals who can navigate the complexities of healthcare transactions.
FAQs
Q1. What formula should I use to determine my medical practice’s value? Medical practice valuation uses multiple approaches rather than a single formula. The most common methods include the income approach (using EBITDA multiples of 6x to 12x), asset-based valuation (adding all assets minus liabilities), market comparison (analyzing similar practice sales), and revenue multiples (typically 0.5x to 2.5x annual revenue). Professional valuators combine these methods to arrive at an accurate valuation, as each approach examines different aspects of your practice’s worth.
Q2. How is EBITDA used in medical practice valuations? EBITDA (Earnings Before Interest, Taxes, Depreciation, and Amortization) serves as the foundation for most healthcare practice valuations because it reflects core operational profitability. Medical practices typically trade at 6x to 12x adjusted EBITDA depending on size and quality. Larger practices generating over $5M in EBITDA command 10x to 12x multiples, while smaller practices with $500K to $1M EBITDA receive 6x to 8x multiples. Well-run practices maintain EBITDA margins between 20% and 35%.
Q3. How does payer mix affect my practice’s valuation? Payer composition significantly impacts both profitability and valuation multiples. Practices with over 60% commercial insurance achieve 7x to 9x EBITDA multiples, while Medicare-heavy practices receive 5x to 6x multiples. This difference exists because commercial insurance reimburses approximately 89% higher than Medicare rates. Medicaid-heavy practices face the steepest valuation discounts due to lowest reimbursement rates and administrative complexity.
Q4. Why does provider dependency reduce practice value? When a single provider generates more than 60% of practice revenue, buyers view this as high transition risk and reduce their offers accordingly. The concern is whether the practice can maintain revenue after ownership changes. Practices with stable production across multiple clinicians demonstrate sustainability beyond current ownership and consistently receive 1 to 2 additional multiple turns compared to single-provider dependent practices.
Q5. How far in advance should I prepare for a practice valuation? Begin your valuation preparation at least two to three years before any planned transaction. This timeline allows you to organize three to five years of financial documentation, normalize earnings by removing personal expenses, address operational weaknesses, and maximize your final outcome. The actual valuation process takes four to eight weeks depending on documentation quality, but early preparation significantly impacts the final valuation multiple you’ll receive.


